- PERSONAL INSURANCE SOLUTIONS
Housing Insurance: Whether You Rent or Own, Protect What Matters Most
Protecting the roof over your head and everything under it:
Or
Your home is more than where you live—it’s likely your biggest financial investment. A solid homeowners policy isn’t just about satisfying a mortgage lender; it safeguards your future against two critical risks:
Your Home & Belongings: Rebuilding after a fire or severe storm costs hundreds of thousands of dollars. Proper coverage pays to repair or rebuild your home, replace your personal property, and cover living costs while repairs are underway.
Your Life Savings: A single slip-and-fall on your walkway or an accidental injury on your property can trigger an expensive lawsuit. Liability coverage steps in to fund your legal defense and settlements—protecting your savings and future income.
Secure your investment. Protect your peace of mind.
Some of our partners for homeowners insurance:

Why Have A Renter's Policy (HO-4):
 There’s a common myth among renters that if something happens to the building, the landlord’s insurance covers whatever is inside.
In reality, it doesn’t cover a single dollar of your personal belongings.
Your landlord’s policy only protects the physical structure—the roof, exterior walls, and hallways. If there’s a kitchen fire, a burst pipe, or a break-in, you’re on the hook to replace your furniture, electronics, and clothing. Even worse, if a guest slips inside your apartment, your personal savings could be exposed to expensive medical or legal bills.
The good news? A renters insurance policy typically costs just $15 to $25 a month (roughly the price of a couple of coffees a week) and covers:
Your personal belongings (even when traveling or kept in your car)
Personal liability protection against accidental injuries or property damage
Temporary living expenses if an emergency makes your unit unlivable
Or
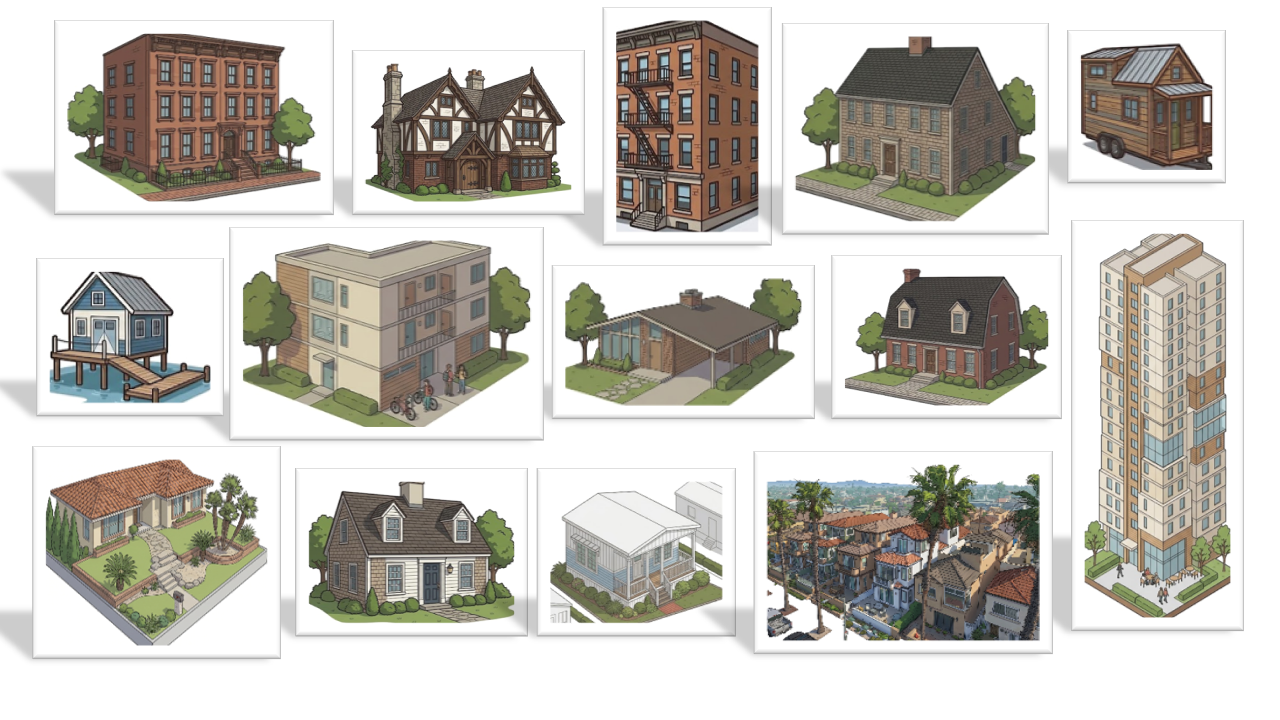
Housing Types Covered by Renters Insurance (HO-4):
• Traditional Apartments & Multi-Family Units
• Single-Family Home Rentals
• Condominiums & Co-ops Rentals
• College Dormitories & Campus Residence Halls
• Single Rooms in Private Homes / Boarding
• Accessory Dwelling Units (ADUs)/In-Law Suites
Landlord Policy (DP-3)
Whether you rent out a single spare room, an entire floor, or a separate building – completely changes your insurance needs.
The Short Answer:
Entire property or separate unit: You almost certainly need a Landlord Policy (DP-3).
A single room in the home you live in: You might not need a whole landlord policy—often, an endorsement (add-on) to your standard homeowners policy is enough.
Which Policy Do You Actually Need?
Your Living Situation | What You Need | Why |
Entire property rented out (You live elsewhere) | Landlord Policy | Standard homeowners insurance does not cover homes you do not live in. |
Multi-family home (You live in one unit, rent the other) | Landlord Policy or Special Homeowners Form | Covers the structure, your rental income if a fire displaces tenants, and tenant slip-and-fall liability. |
A room in your home (You live there full-time) | Homeowners Policy + “Permitted Incidental Occupancy” Rider | Most carriers let you add a simple rental rider to your existing policy without buying a separate contract. |
Short-term / Airbnb / Vrbo | Short-Term Rental Endorsement | Regular landlord policies and standard homeowner policies both usually exclude short-term, nightly stays. |
What a Landlord Policy Protects:
The Building: Fixes walls, floors, aand the roof if damaged by covered events like fires, storms, or pipe bursts.
Premises Liability: Covers your legal fees and medical bills if a tenant or their guest slips, falls, and sues you.
Lost Rental Income: Replaces the rent checks you count on if a covered accident forces the tenants out during repairs.
Your Appliances: Replaces major appliances you supply (stove, fridge, washer/dryer) if destroyed in a covered claim.
Note: A landlord policy NEVER covers the tenant’s personal items.
Always require your renters to carry their own Renters Insurance (HO-4).